How Practice Settings Shape Nurse Practitioner Coverage
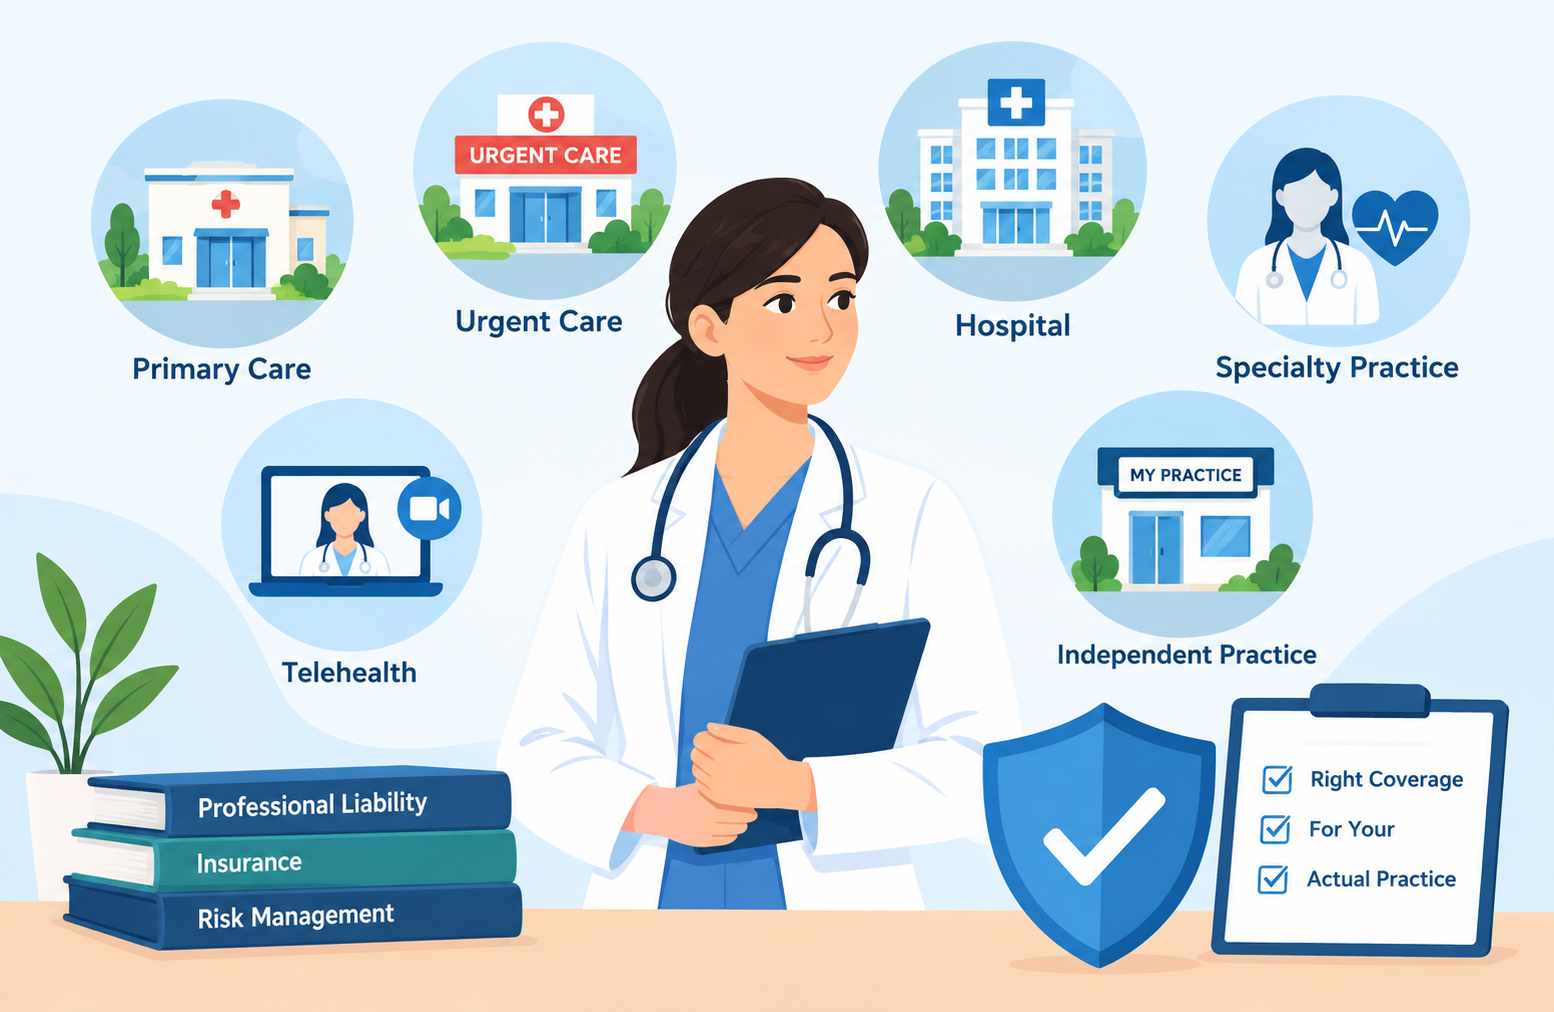
Nurse practitioners work in an increasingly diverse range of healthcare environments. Some spend their careers in primary care clinics, while others provide services in hospitals, urgent care centers, specialty practices, or through virtual appointments. Certain practitioners also establish independent practices where their credentials and local laws permit.
Although these professionals may share similar educational foundations, their daily responsibilities can differ considerably. The setting in which care is delivered can influence clinical expectations, employment relationships, administrative responsibilities, and professional liability considerations. Understanding these differences helps nurse practitioners evaluate whether their insurance arrangements reflect the work they actually perform.
Primary Care Involves Ongoing Patient Relationships
Primary care nurse practitioners often develop long-term relationships with patients.
Their responsibilities may include preventive care, chronic condition management, medication prescribing, diagnostic evaluation, and coordination with specialists.
These activities can involve multiple appointments and decisions over extended periods.
Maintaining organized records and reliable follow-up systems is particularly important.
Practices need procedures for communicating test results, managing referrals, and tracking information that requires additional attention.
From an insurance perspective, practitioners should make sure their professional activities are accurately described.
A policy should be evaluated based on the actual scope of services rather than the general assumption that all primary care practices operate identically.
Urgent Care Creates Different Demands
Urgent care environments often involve patients seeking treatment for immediate concerns.
Nurse practitioners may encounter a broad range of symptoms and conditions, sometimes with limited access to a patient’s complete medical history.
The pace of care can also differ from traditional scheduled appointments.
These circumstances make communication, documentation, clinical assessment, and appropriate referral procedures especially important.
Professionals considering nurse practitioner malpractice insurance for urgent care work should make sure the insurer understands the setting and the nature of the services provided.
Coverage arrangements may differ depending on whether the practitioner is employed, contracted, or working through another professional relationship.
Understanding those distinctions before beginning work can help avoid unnecessary uncertainty.
Hospital-Based Practice Requires Coordination
Hospitals rely on multidisciplinary teams to deliver patient care.
Nurse practitioners may work alongside physicians, nurses, pharmacists, therapists, and other professionals in departments with different clinical responsibilities.
Some practitioners focus on inpatient management, while others work in specialty services or other hospital-based roles.
Clear communication is essential when patient responsibilities shift between professionals.
Documentation, consultations, treatment plans, and transitions of care can all require coordination.
Hospital employment may include professional liability coverage, but practitioners should understand the relevant terms.
Coverage for activities outside the hospital shouldn’t automatically be assumed.
Clinicians who work for multiple organizations may need to examine how different insurance arrangements apply to their separate responsibilities.
Specialty Practice Changes the Clinical Focus
Nurse practitioners may specialize in areas such as family health, psychiatric mental health, pediatrics, adult-gerontology, women’s health, or other fields consistent with their credentials and applicable requirements.
Different specialties can involve different patient populations, procedures, and clinical responsibilities.
A psychiatric mental health nurse practitioner may encounter liability considerations associated with behavioral health assessment and medication management.
A practitioner working in another specialty may face different questions involving procedures, treatment plans, or follow-up care.
Insurance applications should accurately describe the practitioner’s specialty and services.
Practitioners who change specialties or add professional activities should determine whether their insurer needs updated information.
The important consideration is whether coverage aligns with current responsibilities.
Telehealth Expands Where Care Happens
Virtual healthcare allows nurse practitioners to interact with patients without requiring an in-person appointment.
Depending on the services involved, telehealth may support consultations, follow-up visits, medication management, and other appropriate activities.
However, remote care introduces considerations involving technology, communication, documentation, privacy, and professional regulation.
Practitioners should understand where they are legally permitted to provide services.
Licensing and practice requirements can depend on the jurisdiction in which the patient is located.
Insurance should also be reviewed.
An existing policy shouldn’t automatically be assumed to cover every telehealth activity or location.
Nurse practitioners can clarify these issues before expanding virtual services.
Independent Practice Adds Business Responsibilities
Independent practice can provide greater control over certain professional and operational decisions where permitted by law.
It also creates responsibilities beyond direct patient care.
Practice owners may need to manage employees, facilities, contracts, billing systems, technology, records, and other administrative functions.
Professional liability coverage addresses only certain categories of risk.
Other exposures may require separate consideration, including general business liability, property, cyber incidents, and employment-related matters.
A practice owner should avoid assuming that one insurance policy covers every aspect of the business.
Understanding the distinction between professional liability and other commercial insurance can help create a more organized approach to risk management.
Multiple Jobs Can Complicate Insurance Arrangements
Some nurse practitioners work in more than one setting.
A clinician might maintain a primary hospital position while also working occasional shifts at a clinic or providing other professional services.
Different employers may maintain separate insurance arrangements.
Independent contractor relationships can create additional questions about who is responsible for coverage.
Practitioners should review relevant agreements and confirm how insurance applies to each role.
It is particularly important to avoid assuming that coverage through one employer extends to unrelated professional activities.
Clear documentation of coverage arrangements can be useful when managing multiple positions.
State Requirements Can Influence Practice Decisions
Nurse practitioner practice authority and professional requirements vary by jurisdiction.
Depending on the location, applicable rules may address scope of practice, prescribing, collaborative arrangements, licensing, and other professional responsibilities.
Insurance requirements can also arise through employers, facilities, or contracts.
A nurse practitioner moving to another state should review the requirements applicable to that state.
The same applies when providing services across jurisdictional boundaries.
Professional regulation and insurance are related considerations, but they aren’t interchangeable.
A policy doesn’t authorize activities that fall outside a practitioner’s legally permitted scope.
Career Transitions Deserve Advance Planning
Changing practice settings can affect existing insurance arrangements.
A practitioner moving from employment to independent practice may need to obtain new coverage.
Someone leaving a claims-made policy may need to investigate how future claims arising from earlier professional services would be handled.
Depending on the circumstances, extended reporting coverage or another appropriate arrangement may be relevant.
These questions should ideally be resolved before the transition occurs.
Maintaining copies of previous policy documents and employment-related insurance information can also be useful.
Organized records help practitioners understand their coverage history as their careers develop.
The Right Coverage Reflects the Real Practice
There is no single insurance arrangement that automatically fits every nurse practitioner.
Primary care, urgent care, hospital practice, specialty services, telehealth, and independent practice can involve different responsibilities.
Employment status and jurisdiction add further considerations.
The most useful starting point is an accurate understanding of what the practitioner does, where services are delivered, and which professional relationships apply.
Insurance should be reviewed when those circumstances change.
By aligning coverage decisions with actual practice activities, nurse practitioners can approach professional liability planning with greater clarity and confidence.